- /
Retiring in Manchester: Is It the Right Move?
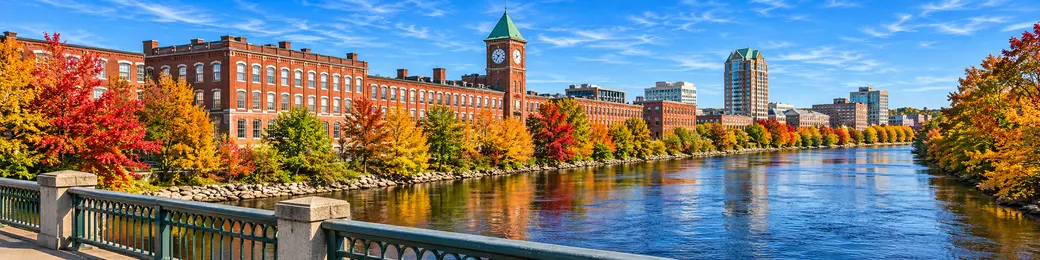
Retiring in Manchester can work well for people who want city services, a four-season lifestyle, and New Hampshire's favorable state-level treatment of retirement income. The trade-offs are just as important: homeownership costs, local property taxes, winter mobility, and access to preferred medical providers all deserve a close look. Manchester is a city in Hillsborough County, New Hampshire, with established neighborhoods, downtown conveniences, hospital access, and outdoor spaces. The right move depends on whether your housing choice and everyday routine remain manageable through every season.
Manchester Retirement: The Quick Overview
Manchester offers a practical retirement setting for downsizers who want services and recreation close to home.
- Housing: Retirement housing includes condominiums, apartments, and established single-family homes, with each option carrying different maintenance and property-tax considerations.
- Retirement income taxes: New Hampshire does not levy a general personal income tax, and its Interest and Dividends Tax was repealed for taxable periods beginning after December 31, 2024 (New Hampshire Department of Revenue Administration).
- Medical access: Elliot Hospital and Catholic Medical Center both provide hospital and emergency services within Manchester.
- Climate: Four distinct seasons, with cold and snowy winter conditions.
- Lifestyle draw: The city's Heritage Trail connects recreational corridors and access points including Arms Park along the Merrimack River (City of Manchester Heritage Trail).
Manchester by the Numbers
Manchester's most useful retirement figures are often property-specific rather than citywide, especially for a buyer comparing taxes, association fees, accessibility, and winter upkeep. Still, a few current numbers help frame the decision.
Property taxes: For tax year 2025, the City of Manchester lists a property-tax rate of $20.24 per $1,000 of assessed valuation, up from $19.58 the year before. The city also notes that its 2025 equalization ratio was 64.8%, meaning assessments sit well below current market values on average. A prospective buyer should not treat a listing price as a tax estimate without reviewing the actual assessment and current municipal records (City of Manchester tax rates). The 2026 ratio had not yet been established at the time of writing.
Home prices: Based on local MLS data, Manchester single-family homes sold at a median price of $470,000 in September 2026, across 62 closed sales. Inventory was 0.9 months of supply, homes averaged 18 days on market, and buyers paid an average of 99.8% of list price. For retirees who already own a home in the city, those numbers suggest steady demand. For retirees buying, they signal that well-kept homes still move quickly, so it pays to have financing and priorities sorted before touring.
Why Retirees Choose Manchester
Manchester appeals to retirees who want an active daily routine without relying on a resort-style setting. The city combines established residential streets with a downtown and riverfront environment where errands, dining, events, and short outdoor outings can be part of the same week.
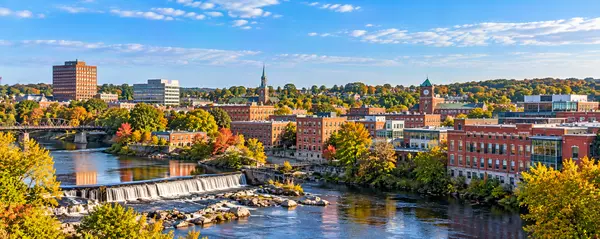
The strongest lifestyle advantage is variety at a manageable scale. The Heritage Trail includes 6.1 miles of dedicated segments and access points at Stark Park, River Road, and Arms Park. Arms Park sits between Commercial Street and the Merrimack River, with benches and a scenic riverside walk. Those options can suit a retiree looking for regular movement without committing to a long hike or a drive out of town.
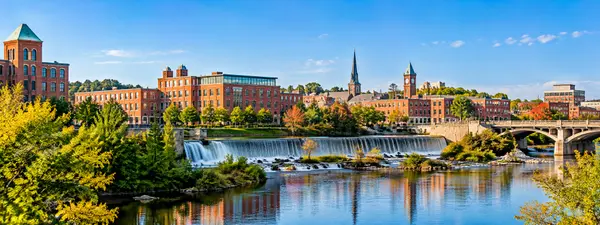
Downtown and the historic Millyard add another layer to retirement life. Restaurants, local businesses, arts programming, and events at SNHU Arena provide indoor options when weather is less cooperative. Livingston Park, in the North End, includes Dorrs Pond and offers fishing and seasonal ice skating when conditions allow.
Manchester is especially worth considering for retirees who prefer an urban-suburban balance: nearby healthcare, familiar neighborhoods, outdoor access, and regional road connections. It may be less appealing for someone who wants warm winters, newer master-planned retirement development, or a fully car-free lifestyle.
Cost of Living in Manchester
Living costs in Manchester require a property-by-property budget, particularly for retirees using a fixed income. Housing is usually the largest variable because a downtown condominium, a rental apartment, and an older detached home can create very different monthly obligations.
Buying can offer stability and control over the home, but ownership costs extend beyond the mortgage or purchase price. Property taxes, homeowners insurance, heating, repairs, snow removal, and association fees can all change the total. A lower-maintenance condominium may reduce exterior responsibilities, while an older single-family home can offer more space but require more planning for upkeep.
Renting can simplify repair responsibilities and may be useful for retirees who want to test a neighborhood before buying. Still, renters should review lease renewal terms, parking, elevator access, laundry arrangements, heating responsibility, and whether utilities are included.
Groceries, transportation, and healthcare costs depend heavily on lifestyle. A retiree living near downtown amenities may drive less for errands, while a household making frequent regional trips may want to allow more for fuel, parking, and vehicle maintenance. Healthcare premiums and prescription costs also vary by Medicare plan and provider network.
The practical approach is to compare complete monthly costs for each home. Use the same retirement-budget checklist for every option: monthly housing payment, tax bill, insurance, utilities, association fees, parking, accessibility, winter maintenance, and travel time to medical appointments.
Retirement Income and Taxes in Manchester
New Hampshire's tax structure is a meaningful advantage for many retirees because the state does not impose a general personal income tax. The state's former Interest and Dividends Tax was repealed for tax periods beginning after December 31, 2024. As a result, Social Security benefits, pension income, and withdrawals from traditional retirement accounts are generally not subject to a New Hampshire personal income tax.
Federal taxes still matter. Social Security taxation at the federal level can depend on combined income and filing status. Pension income and withdrawals from traditional 401(k) and IRA accounts may also affect a household's federal tax position. A retirement move should include a conversation with a qualified tax professional before changing residency or setting a long-term withdrawal plan.
Property taxes remain a major local planning issue. Manchester offers an elderly exemption for qualifying homeowners, deducting the following from assessed value based on age as of April 1:
| Applicant age | Assessed-value deduction |
|---|---|
| 65 to 74 | $240,000 |
| 75 to 79 | $325,000 |
| 80 and older | $435,000 |
Eligibility includes ownership of record on or before April 1, three consecutive years of New Hampshire residency, and living in the home. Total income cannot exceed $47,000 for a single person or $63,000 for a married person, and assets (excluding the home) are capped at $100,000 for single taxpayers and $130,000 for married taxpayers, measured as of December 31 of the prior year. There is more context on how property tax relief works for local retirees.
New Hampshire does not have an estate tax or inheritance tax. Even so, estate planning may still involve federal rules and the laws of other states where property or heirs are located.
The retirement takeaway is clear: favorable state income-tax treatment can help a budget, but property taxes and full housing costs still need careful review before purchasing.
Tax Snapshot for Retirees
- State income tax: New Hampshire has no general personal income tax on wages or retirement income.
- Interest and dividends: The former state Interest and Dividends Tax was repealed for taxable periods beginning after December 31, 2024.
- Elderly exemption: Eligible Manchester homeowners may receive an assessed-value deduction of $240,000 to $435,000 based on age, subject to residency, income, asset, and ownership requirements.
- Home-sale gains: Qualifying primary-residence sellers may exclude up to $250,000 of federal capital gain, or up to $500,000 for many married couples filing jointly. New Hampshire does not add a state tax on that gain.
- Estate planning: New Hampshire does not impose a state estate or inheritance tax, although federal rules may still apply.
Healthcare in Manchester
Manchester provides in-city hospital access through Elliot Hospital and Catholic Medical Center, which can be a practical advantage for retirees who want acute-care and emergency services nearby. Living in the same city as a hospital can make routine appointments, urgent visits, pharmacy trips, and caregiver logistics easier than they may be in a more rural setting.
Hospital proximity is only one part of healthcare planning. Before selecting a home, retirees should verify that preferred primary-care physicians and specialists accept their Medicare coverage. It is also wise to identify nearby pharmacies, evaluate transportation options, and consider whether winter driving conditions could affect appointments.
Medicare's Care Compare tool can help households review hospital quality information and available ratings, though a rating should be only one factor in a decision. Provider relationships, appointment availability, care coordination, and insurance-network fit are equally important.
For a downsizer, the route between home and care providers can be as important as the neighborhood itself. Look for manageable parking, a straightforward entrance, limited stairs, reliable snow clearing, and convenient access to main roads. Specialty appointment availability can vary by practice and insurance plan, so confirm those details before committing to a purchase or lease.
Where Retirees Live in Manchester
Manchester offers several housing patterns that can work for retirees, although accessibility and maintenance needs usually matter more than a neighborhood name alone. Browsing homes for sale around Manchester can help you compare layouts and price points.
Downtown and the Millyard can suit active couples, single retirees, and downsizers who want restaurants, local events, river access, and a more walkable routine. Condominiums and apartments may reduce exterior maintenance, but prospective residents should examine elevator access, parking, association fees, unit layout, and building noise.
The North End offers established residential streets and a more traditional neighborhood feel. It can appeal to retirees who want a detached home, private outdoor space, and access to city services. The trade-off is greater responsibility for repairs, landscaping, heating, and snow removal.
The West Side and other established residential areas can offer a range of housing types for people prioritizing space, road access, or a quieter setting. Downsizers should focus on practical features such as first-floor living, bathroom layout, driveway grade, handrails, and the distance to groceries and medical providers.
Lower-maintenance condos and townhomes throughout the city may work well for snowbirds or retirees who want fewer exterior chores. Review the association's maintenance scope, reserve planning, pet rules, parking, and any restrictions that could affect future flexibility.
For buyers considering higher-end homes, the same checklist applies with extra attention to systems, finishes, and long-term maintenance costs, since larger or more customized properties typically carry bigger tax bills and upkeep budgets.
Already Own in Manchester? Planning Your Sale
Many people reading about retiring in Manchester already live here and are deciding whether to stay in a larger home or move to something more manageable in the same city. If that is you, your current home is likely the biggest piece of the retirement budget.
A few practical steps help:
- Get a property-specific home valuation so your planning starts from a realistic number rather than a general median.
- Account for New Hampshire's seller-side transfer tax of $0.75 per $100 of the sale price, which is $3,525 on a $470,000 sale, along with brokerage, title, and moving costs.
- Decide early whether you plan to sell first or buy first, since that choice shapes your timeline and financing.
- Keep in mind that sale proceeds held in the bank count toward the elderly exemption's asset limit at your next Manchester home.
For a broader look at conditions ahead, there is also an outlook on where the Manchester housing market may be heading.
Climate and Lifestyle: What Daily Life Looks Like
Manchester has a true four-season climate, and winter preparation should be part of any retirement decision. Cold temperatures, snow, icy sidewalks, and shorter daylight hours can make a home's entryway, parking arrangement, and snow-removal plan more important than extra square footage.
Spring through fall offer more opportunities for outdoor routines. The Heritage Trail, Arms Park, Livingston Park, and the Merrimack River setting give residents options for walking, relaxing, fishing, and attending community events. Downtown restaurants, arts programming, and arena events provide useful indoor alternatives when weather limits outdoor plans.
The most comfortable retirement setup is often one that supports ordinary errands in January as easily as it supports a riverside walk in July. A covered parking space, a level entry, reliable snow clearing, and a short route to groceries or healthcare can materially improve daily life.
Pro-Tip: Evaluate a potential home through a winter lens first. Drive the route to groceries, medical offices, and downtown, then assess parking, sidewalks, entry steps, and snow-removal responsibilities.
Planning a Retirement Move? Join a Live Downsizing Webinar
If you are weighing whether to stay, downsize, or move within Manchester, a live webinar can help you sort through the questions before you meet with anyone one-on-one. Joanne hosts live seller sessions focused on downsizing and selling for retirement.
Sessions cover:
- Estimating your home's value and what you may net after costs
- Comparing condos, smaller homes, and other retirement housing options
- How New Hampshire taxes, local exemptions, and federal home-sale rules affect your plan
- Sequencing a sale and purchase without a stressful gap
- Practical tips for decluttering and the move itself
Sessions are live and interactive, with limited seats. Upcoming dates are available through the contact page.
Ready to Explore Retiring in Manchester?
Joanne Tassoni, Broker Associate with Heart & Home with Joanne | REAL Broker LLC and a Seller Representative Specialist (SRS), helps Manchester retirees and downsizers plan both sides of a move. Her services include:
- Home valuations, marketing analysis, and pricing strategy for your current home
- Listing and selling representation
- Home buying assistance and property search for condos, townhomes, and single-level homes
- Negotiation and contract support
- Closing coordination so both transactions stay on track
Call or text (603) 722-5235, email JoanneTassoniBroker@gmail.com, or reach out through the contact page for a no-pressure conversation about downsizing options, housing priorities, and current local conditions.
Frequently Asked Questions
Is Manchester a good place to retire?
Manchester can be a good fit for retirees who value nearby hospital services, established neighborhoods, riverside recreation, and a city with both downtown activity and quieter residential areas. It is best suited to people who budget realistically for housing costs, local property taxes, and winter maintenance.
How affordable is Manchester on a fixed retirement income?
Affordability depends most on the home or rental you choose and its complete monthly cost. Retirees should calculate property taxes, insurance, utilities, association fees, parking, maintenance, and transportation rather than comparing purchase prices alone. For tax year 2025, Manchester's property-tax rate was $20.24 per $1,000 of assessed value.
Is healthcare access adequate in Manchester for retirees?
Manchester has in-city access to Elliot Hospital, Catholic Medical Center, and a range of medical providers, which can reduce travel for many routine and urgent needs. Before moving, confirm Medicare acceptance, prescription coverage, specialist availability, and the route from a potential home to preferred providers.
What are the property tax and retirement income tax benefits in New Hampshire?
New Hampshire does not levy a general personal income tax, and the former Interest and Dividends Tax was repealed for periods beginning after December 31, 2024. Qualifying Manchester homeowners age 65 and older may also be eligible for an elderly exemption of $240,000 to $435,000 off assessed value, subject to income, asset, ownership, and residency requirements.
What types of housing are available for retirees in Manchester?
Retirees can choose from downtown condominiums, Millyard residences, apartments, townhomes, and detached homes in established neighborhoods. The strongest options are usually those with manageable stairs, parking, heating costs, snow-removal arrangements, and access to everyday services.
What is the social and lifestyle scene like for retirees in Manchester?
Manchester offers a mix of riverfront walks, trails, parks, dining, arts programming, and arena events. Retirees who enjoy a four-season routine and want local services close at hand may find the city's urban-suburban balance appealing.
Categories
Recent Posts